What is the scope and market size of the Subsea Manifolds Market?
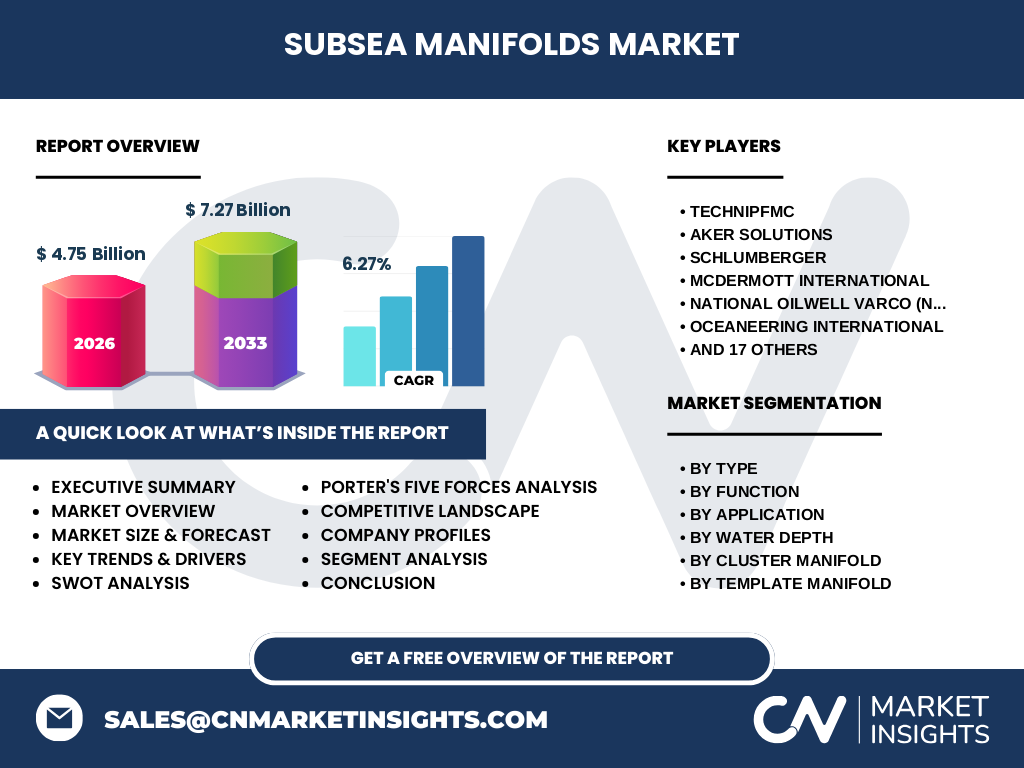
Our analysis indicates that the Subsea Manifolds Market is valued at 4.75 Billion in 2026. This proprietary market sizing encompasses critical subsea architecture designed to route hydrocarbons and inject fluids across deepwater and ultra-deepwater plays, operating under extreme marine pressures and governed by stringent API and ISO compliance standards.
Structural Growth Drivers and Market Restraints
The market is propelled by a 6.27% CAGR, driven by escalating deepwater discoveries in offshore Guyana, Brazil, and the Gulf of Mexico. Conversely, high capital expenditure and severe supply chain bottlenecks for corrosion-resistant alloys, such as Inconel cladding, act as primary restraints limiting rapid project execution.
Emerging Trends Shaping Subsea Manifolds Market Industry Trends
Operators are aggressively prioritizing all-electric subsea architectures to replace traditional hydraulic control systems. This evolution significantly lowers carbon footprints and enables real-time digital twin monitoring through advanced fiber-optic telemetry integrated directly into manifold structures.
How did the COVID-19 pandemic impact the Subsea Manifolds Market?
The pandemic triggered severe capital expenditure freezes, delaying complex subsea tie-back projects worldwide. However, the post-crisis recovery trajectory demonstrates robust resilience, as operators leverage standardized multi-slot template designs to accelerate time-to-first-oil and maximize brownfield asset efficiency.
Competitive Benchmarking in the Subsea Manifolds Market
The market features high industry concentration dominated by tier-one EPCIs. TechnipFMC and OneSubsea leverage integrated Subsea Production Systems (SPS) to secure lump-sum contracts, while specialized players like Dril-Quip compete via proprietary connector technologies and agile manufacturing footprints.
Executive Summary of the Subsea Manifolds Market Report
Our comprehensive executive analysis projects the market to surge from 4.75 Billion to 7.27 Billion by 2033. This expansion is underpinned by sustained offshore exploration budgets, technological leaps in all-electric control systems, and modular manifold designs that mitigate deepwater operational risks.
Market Forecast Projections from 2027 to 2033
Driven by a steady 6.27% CAGR, the valuation will climb from 2027 to reach 7.27 Billion by 2033. This sustained trajectory reflects accelerated sanctioning of deepwater greenfield developments and enhanced oil recovery (EOR) projects requiring complex injection manifolds.
Segmentation Analysis of the Subsea Manifolds Market
Our taxonomy segments the market by Type (Template, Cluster, PLEM), Function (Choke And Kill, Squeeze, Frac, Production, Injection), Application (Production, Injection), and Water Depth (Shallow, Deep, Ultra Deep Water). Cluster manifolds and ultra-deepwater applications command the highest revenue shares due to complex subsea tie-back requirements.
Regional Market Analysis and Geographic Performance
Geographic distribution heavily favors the Americas and West Africa, anchored by prolific pre-salt basins in offshore Brazil and deepwater discoveries in the US Gulf of Mexico. Localized regulatory frameworks enforced by agencies like the BSEE dictate strict structural integrity requirements for all deployed manifold systems.
In-Depth Regional Review of High-Growth Basins
The Latin American market leads global demand, fueled by Petrobras' aggressive deployment of floating production storage and offloading (FPSO) units connected to complex subsea networks. Meanwhile, the North American shelf and deepwater sectors focus on brownfield tie-backs utilizing standardized Pipeline End Manifolds (PLEM).
Strategic Company Profiles in the Subsea Manifolds Market
Industry leaders like Aker Solutions and Saipem focus on modular, scalable manifold designs that reduce fabrication lead times. Concurrently, service giants such as Schlumberger and Halliburton integrate subsea processing capabilities directly into production manifolds to enhance reservoir yield.
Porter's Five Forces Analysis of Competitive Dynamics
Bargaining power of buyers remains moderate-to-high, as major oil companies demand custom metallurgical specifications and cost-competitive EPCI bundling. Threat of new entrants is remarkably low due to massive capital expenditure barriers, stringent API testing certifications, and established long-term supplier relationships.
SWOT Analysis of the Subsea Manifolds Market
Key strengths include robust technological innovation in digital monitoring and high-pressure/high-temperature (HPHT) metallurgy. Weaknesses stem from vulnerability to crude price volatility. Opportunities lie in electrification and carbon capture storage (CCS) injection manifolds, while threats involve geopolitical supply chain disruptions.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction for super-duplex stainless steels and nickel alloys. These are forged into structural blocks by tier-two metallurgical suppliers, engineered into proprietary manifold skids by companies like Wood Group and Kongsberg Maritime, and finally installed offshore by heavy-lift vessel operators.
Investment Insights and Strategic Recommendations
Investors should target technology innovators specializing in all-electric actuation and autonomous underwater vehicle (AUV) docking manifolds. Companies positioned to support brownfield life-extension projects and carbon capture injection infrastructure will capture disproportionate margin expansion through 2033.
Conclusion and Key Takeaways for Market Stakeholders
The Subsea Manifolds Market is transitioning into a high-tech era characterized by digital integration and carbon-conscious engineering. Reaching 7.27 Billion by 2033 at a 6.27% CAGR, success belongs to agile manufacturers embracing modularity, standardization, and low-carbon subsea architectures.
Research Methodology for Baseline Market Estimates
Our baseline estimates are triangulated using a rigorous methodology combining secondary macroeconomic indicators, official trade registry customs data, and extensive primary interviews with offshore project engineers, subsea supply chain directors, and regulatory compliance officers across major energy hubs.
Scope of the Report and Operational Limitations
This report covers global commercial deployment of subsea manifold systems across shallow, deep, and ultra-deepwater environments from 2026 to 2033. Excluded from this scope are surface topside manifold systems, land-based wellhead equipment, and non-commercial prototype technologies still undergoing subsea basin trials.
Recent Developments and Strategic Industry Moves
Recent market activity highlights major consolidation and technological partnerships, such as TechnipFMC securing alliance agreements for standardized subsea architecture deployment. Furthermore, firms like Allseas Group are investing in specialized installation vessels to handle heavier multi-slot template manifolds safely in ultra-deepwater locations.